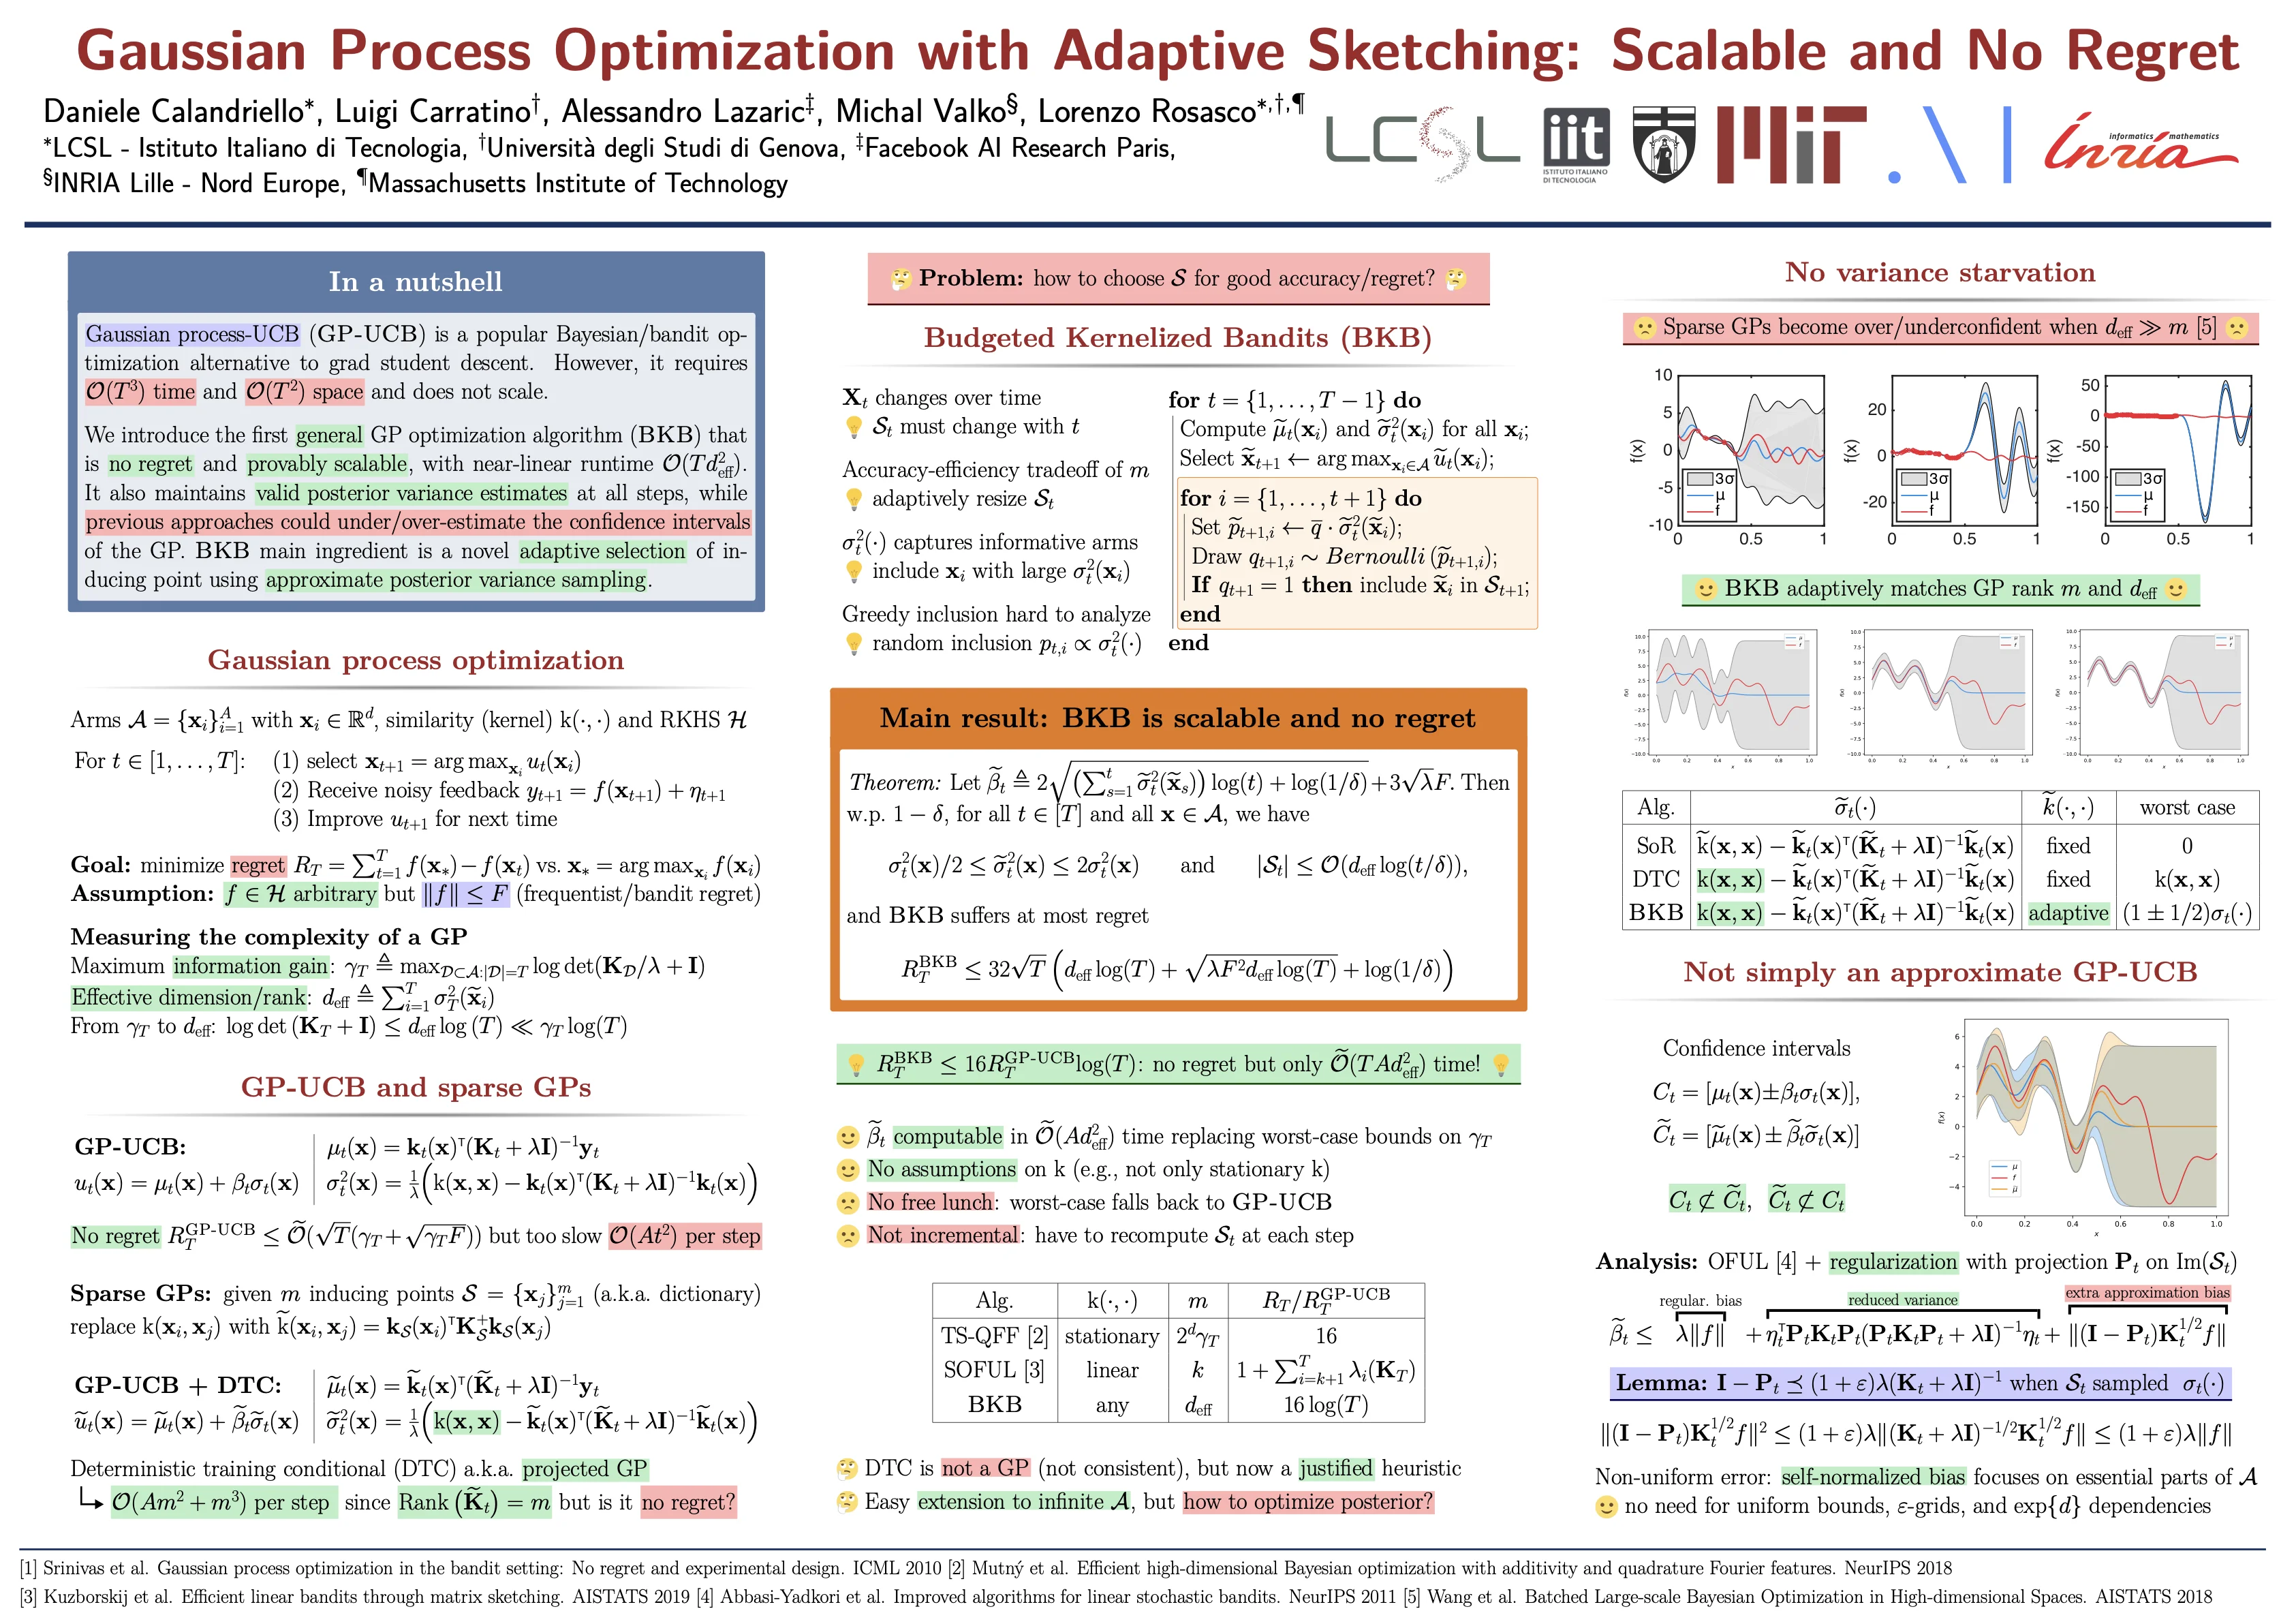
Gaussian process optimization with adaptive sketching: Scalable and no regret
2019 · in (COLT 2019) and (ICML 2019 - NEGDEP) and (SWSL 2019)
Abstract
Gaussian processes (GP) are a popular Bayesian approach for the optimization of black-box functions. Despite their effectiveness in simple problems, GP-based algorithms hardly scale to complex high-dimensional functions, as their per-iteration time and space cost is at least quadratic in the number of dimensions d and iterations t. Given a set of A alternative to choose from, the overall runtime O(t3A) quickly becomes prohibitive. In this paper, we introduce BKB (budgeted kernelized bandit), a novel approximate GP algorithm for optimization under bandit feedback that achieves near-optimal regret (and hence near-optimal convergence rate) with near-constant per-iteration complexity and no assumption on the input space or covariance of the GP. Combining a kernelized linear bandit algorithm (GP-UCB) with randomized matrix sketching technique (i.e., leverage score sampling), we prove that selecting inducing points based on their posterior variance gives an accurate low-rank approximation of the GP, preserving variance estimates and confidence intervals. As a consequence, BKB does not suffer from variance starvation, an important problem faced by many previous sparse GP approximations. Moreover, we show that our procedure selects at most Õ (deff) points, where deff is the effective dimension of the explored space, which is typically much smaller than both d and t. This greatly reduces the dimensionality of the problem, thus leading to a O(TAd2eff) runtime and O(Adeff) space complexity.
PDF · Conference on Learning Theory · arXiv preprint · bibtex · video · talk · poster · poster (image) · DOI